An underpaid business insurance claim can leave a company facing repair bills, damaged equipment, lost inventory, or interrupted operations that are not fully reflected in the insurer’s estimate. For business owners reviewing a commercial property insurance claim, comparing the estimate with the actual damage, repair costs, and supporting records can help identify possible gaps. In this blog, Alpha Public Insurance Adjusters explains why underpayment may occur and what businesses can review before requesting another assessment.
Why Do Underpaid Insurance Claims Occur?
Underpayment in commercial property insurance claims can occur for several reasons. Often, it results from overlooked building damage, contents, equipment, inventory, repair costs, or business interruption losses. Here are some common causes:
Overlooked Building Damage
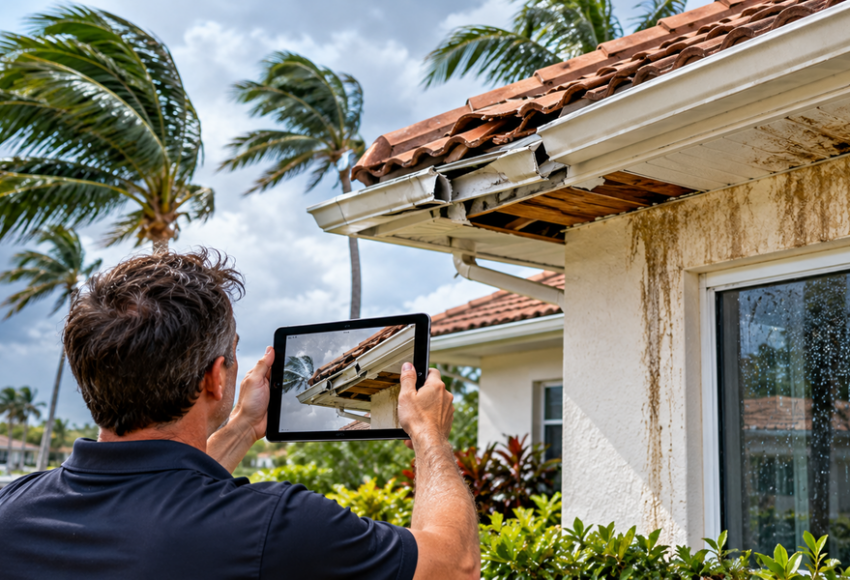
After a significant event such as a storm or fire, visible damage may be only part of the damage. Structural issues, water damage, or electrical problems might be hidden from plain sight. Insurance adjusters may overlook these aspects, leading to an underpaid claim.
Contents, Equipment, and Inventory
Insurance policies often cover the building as well as the contents within it, including equipment and inventory. Inaccurate valuations or missed items during the assessment can result in underpayment. Ensuring that all business assets are accounted for in your claim is important.
Repair Costs
The cost of repairs can be underestimated if the insurer’s estimate does not reflect current market rates or the full scope of necessary work. This difference can lead to a difference between the estimate and repair costs to restore your business property fully.
Business Interruption Losses
When a business is unable to operate normally due to property damage, the resulting loss of income is typically covered under business interruption insurance. However, calculating these losses can be complex, and errors here can affect the compensation received.
Reviewing the Insurer’s Estimate
Once you receive an estimate from your insurer, it’s critical to scrutinize it carefully. Here’s a practical process for reviewing the insurer’s estimate and gathering supporting documentation:
Step 1: Detailed Examination of the Estimate
Begin by comparing the insurer’s estimate with the actual damage and loss your business has incurred. Check for any differences in the scope of work, materials, and costs. If necessary, seek a second opinion from a professional contractor or a public adjuster.
Step 2: Gather Supporting Documentation
Documenting the damage thoroughly is important. Take photographs and videos of all affected areas and create an itemized inventory of damaged items, including receipts and proof of ownership. This documentation will support your case if you need to dispute the insurer’s assessment.
Step 3: Review Policy Details
Understanding your policy’s terms and conditions is important. Ensure that you are aware of what is covered and any exclusions or limitations that might apply. This knowledge can help you determine whether the insurer’s estimate reflects the applicable policy terms.
Steps to Take When a Claim Is Underpaid
If you find that your commercial property insurance claim has been underpaid, there are steps you can take to address the issue effectively:
Contact the Insurance Company
Start by contacting your insurance company to discuss the differences. Provide them with the documentation you have gathered and clearly explain why you believe the claim is underpaid. It’s important to maintain a professional and cooperative tone during these discussions.
Request a Reassessment
If initial discussions do not resolve the issue, formally request a reassessment of your claim. This request should be accompanied by all relevant documentation and any additional estimates you’ve obtained.
Consider Professional Assistance
In cases where negotiations with the insurer are unproductive, consider hiring a public adjuster or a legal professional specializing in commercial insurance claims in Florida. These experts can provide valuable insights and negotiate on your behalf to achieve a fair settlement.
Preventing Future Underpayments
While dealing with an underpaid claim is challenging, there are steps business owners can take to prevent similar issues in the future:
Regular Policy Reviews
Conduct regular reviews of your insurance policy to ensure it adequately covers your business assets and potential risks. Updating your policy as your business grows or changes can prevent coverage gaps and ensure sufficient protection.
Comprehensive Documentation
Maintain detailed records of all business assets, including receipts, photos, and appraisals. This documentation will be invaluable in the event of a claim, providing clear evidence of your assets’ value and condition.
Proactive Risk Management
Implementing risk management strategies can reduce the likelihood of future claims. Regular maintenance, safety protocols, and employee training can all contribute to minimizing potential losses and protecting your business property.
Dealing with an underpaid commercial property insurance claim can be difficult to manage, but understanding the steps to take and the resources available can make the process more manageable. By thoroughly reviewing the insurer’s estimate, gathering comprehensive documentation, and seeking professional assistance when necessary, business owners can work towards a fair settlement. At Alpha Public Insurance Adjusters, we understand the complexities of commercial insurance claims in Florida and are here to support business owners in protecting their assets and ensuring fair compensation.
Concerned that your business insurance payment does not reflect all of the documented damage or losses? Contact Alpha Public Insurance Adjusters to discuss your commercial property insurance claim, insurer estimate, repair costs, damaged equipment or inventory, and supporting documentation.